CashBook - Balance & Expense

- 475.00 Reviews
- 3.8
- Downloads
- 5,000,000+
Our take on CashBook - Balance & Expense from Appgk
Small businesses often lose track of money in a surprisingly simple way: a sale is remembered, an expense is postponed, and by the end of the day the cash balance is more of a guess than a fact. I have used CashBook - Balance & Expense with that problem in mind, and its main value is not flashy automation. It gives you a place to record the movement of money while it is still fresh, so you do not have to reconstruct the day from receipts, messages, and memory.
This is a free business app from Obopay – Payment Wallet for Businesses, designed around cash-flow awareness, daily balances, income, and expenses. It is available to everyone in its age rating, runs on Android 7.0 or later, and the current version is 8.7.3. I would describe it as a practical cash book rather than a full accounting package: useful for making daily money visible, but not a replacement for professional bookkeeping when your business needs formal accounts, tax preparation, payroll, or complex reporting.
Why a simple cash record can save more time than expected
The recurring problem is not always a lack of financial information. It is having that information scattered across too many places. A shop owner may know what came in during the morning, remember buying supplies at lunch, and still be unsure whether the cash drawer should contain the amount expected at closing. A freelancer may receive several payments and pay for transport or materials without recording either one immediately. The individual transactions are easy; the daily picture is what disappears.
CashBook addresses that gap by putting income and expenses into one running record. In my experience, the useful habit is to open it at the moment a transaction happens, enter the amount, and move on. That is less demanding than trying to remember everything later. The app becomes a lightweight routine: record the movement, check the balance, and use the result to decide what can safely be spent or set aside.
Best Parts of CashBook - Balance & Expense
Things to Keep in Mind About CashBook - Balance & Expense
That focus also explains what the app is not. It does not turn a small operation into an enterprise resource planning system, and I would not choose it as the sole tool for a company with multiple layers of approval, inventory valuation, invoicing, or detailed financial statements. Its strength is the immediate cash view. If that is the problem you actually have, the narrow scope works in its favor.
The app has reached more than five million installs and holds an average rating of 3.8 from roughly two hundred thousand ratings. Those figures suggest that it has found a substantial audience, while the rating also tells me to keep expectations realistic: it is useful for many people, but the experience will not feel equally complete for every type of business.
News and Features Related to CashBook - Balance & Expense

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
News
Moovit Review: A More Reliable Way to Navigate Everyday Transit
News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
Getting to a useful first record
The first setup should be approached as a clean starting point, not as an attempt to rebuild your entire financial history. I would begin with the balance you can actually verify, then enter new income and expenses from that point forward. Importing a pile of old notes mentally is exactly the kind of task that makes a bookkeeping tool feel like work before it becomes helpful.
A good first session is short and practical. Decide what you want the balance to represent, such as cash currently available for daily operations, and keep that meaning consistent. Then record one recent income item and one recent expense. This quickly exposes whether the app fits the way you think about money. If you prefer a simple running total, the approach feels natural. If you need several formal accounts reconciled against statements, you may notice the limits immediately.
Don't want to read the full review?
I also recommend choosing descriptions that will still make sense later. “Supplies” is more useful than “purchase,” while “delivery fuel” is more informative than “expense.” This is a small detail, but it changes the value of the history. A cash book is only as useful as the decisions you can make from its entries. Clear labels help you understand why the balance changed instead of merely seeing that it changed.
Another worthwhile habit is separating personal spending from business spending before you enter anything. If you use business cash for a personal purchase, record it in a way that makes the withdrawal obvious rather than hiding it among operating costs. That distinction prevents a common mistake: believing the business is spending too much on supplies when the real issue is that the owner is taking money out without marking it clearly.
Screenshots
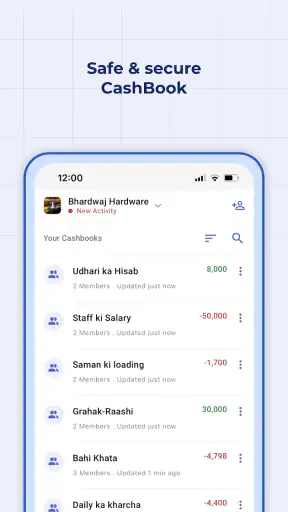
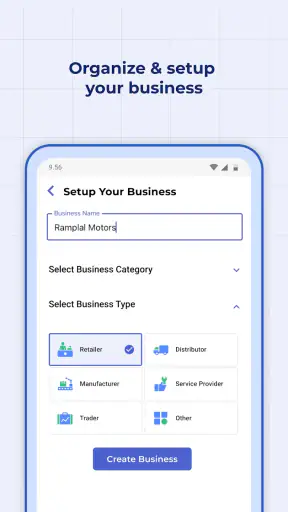
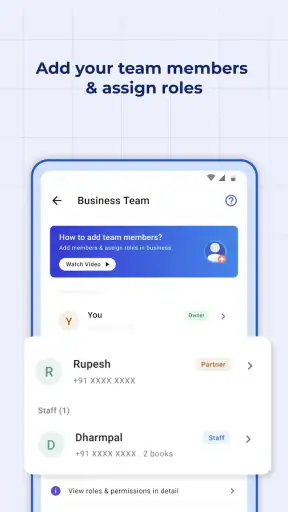
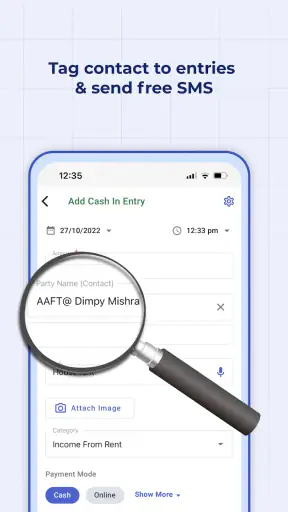
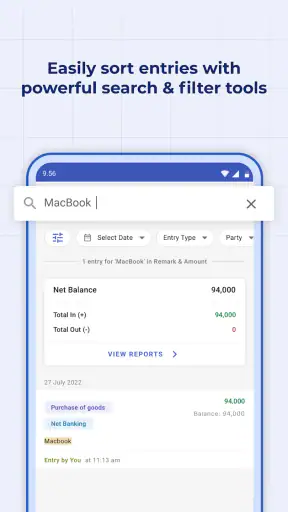
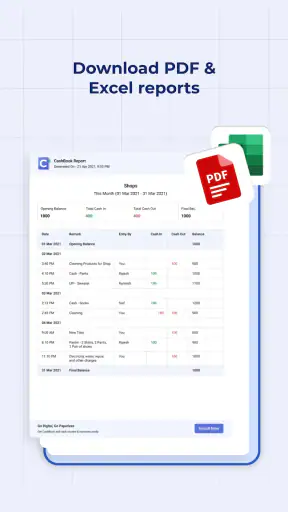
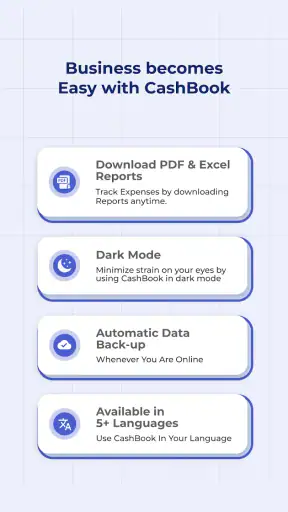
The free price makes experimentation easy, although the app includes in-app purchases ranging from $2.49 to $549.99 per item. I would not treat that range as a reason to buy anything immediately. Start with the workflow you need, see whether the daily record stays accurate, and only then consider whether an optional purchase is relevant to your use. The important test is whether you keep recording transactions consistently, not whether the app offers more room for expansion.
How it fits into an ordinary working day
Imagine a small food stall beginning the morning with a known amount of cash. During the day, customers pay for orders, the owner buys ingredients, and a delivery charge appears unexpectedly. Instead of keeping three numbers in memory, the owner records each movement as it happens. Before closing, the balance gives a quick check against the cash physically available. If the two do not match, the discrepancy can be investigated while the day is still easy to remember.
That scenario shows the app at its best. It does not need to predict sales or make a business decision for you. It reduces the delay between an event and its record. The shorter that delay, the less likely a transaction is to be forgotten or assigned to the wrong day. For people who work alone, that can be more valuable than a long list of advanced accounting tools they never open.
A second scenario is a freelancer handling irregular income. One week may include a client payment, a software renewal, local travel, and a small equipment purchase. A conventional notes app can store those amounts, but it does not naturally turn them into a running cash picture. A spreadsheet can do more, but it requires a structure that may be annoying to maintain on a phone. CashBook sits between those choices: more purposeful than loose notes and less demanding than building your own financial workbook.
There is also a useful end-of-day workflow. I would record the last transaction, check the displayed balance, and compare it with the amount that should be available. If there is a difference, I would correct the record while the reason is still visible. This is not glamorous, but it is the kind of routine that prevents a small error from becoming a week of uncertainty.
For households, the app can be useful in a similar way, especially when one person wants to track a shared cash budget without setting up a complicated finance system. However, I would be careful about using it as a complete household finance solution if you need bank synchronization, investment tracking, bill reminders, or detailed category analysis. Its practical center remains the cash book, not a broad personal-finance dashboard.
Where the app removes friction
The main friction it removes is the need to translate everyday money movement into a more formal system before you can understand it. Many people avoid spreadsheets because they feel too structured, while notes become messy as soon as transactions accumulate. A dedicated cash record gives each entry a clear purpose and keeps the balance connected to the activity that produced it.
That simplicity has a second benefit: it encourages more frequent recording. A financial tool that takes too much effort is often used only when something goes wrong. A focused cash-book workflow is better suited to quick entries throughout the day. In my view, the best measure of this app is not how impressive it looks during a first launch, but whether it becomes part of your closing routine after the novelty wears off.
It can also reduce a subtle form of decision fatigue. When you know the current balance, you do not have to repeatedly ask whether a small purchase is affordable. You can check the record and make the decision with a clearer boundary. That is especially helpful for businesses where cash received today must cover supplies, transport, or other immediate needs before the next payment arrives.
Compared with a paper notebook, the app offers a more convenient way to keep a running digital record and review recent movement without carrying another object. Paper still has advantages for people who prefer writing by hand or need a visible counter beside a till. Compared with a spreadsheet, CashBook should feel quicker for straightforward entries, while a spreadsheet remains better when you need custom formulas, several linked sheets, or detailed analysis. Compared with a full accounting application, it is easier to approach but much narrower in scope.
That trade-off matters. If your business has grown to the point where cash entries must connect to invoices, customer balances, inventory, tax categories, and formal reports, choosing a simpler tool may create extra work later. On the other hand, adopting a heavy accounting system for a tiny operation can lead to its own failure: the system becomes so burdensome that transactions go unrecorded. CashBook is most convincing in the space between those extremes.
Practical habits that make the record more reliable
The first advanced habit is to record withdrawals and transfers as deliberately as sales and purchases. Owners often focus on money paid by customers and forget that taking cash out of the business changes the balance just as much. If you mark those movements clearly, the daily total becomes a management tool rather than a vague cash estimate.
The second is to use a consistent moment for review. I prefer checking after the final transaction of the day, not only when the balance feels wrong. A routine review catches forgotten entries and makes unusual changes easier to explain. It also gives you a natural point to decide whether tomorrow’s spending should be reduced or whether a payment needs to be followed up.
The third is to avoid using descriptions as a substitute for a plan. A long list of detailed labels can look organized while still failing to answer the important question: where is cash going repeatedly? Use descriptions that help you recognize the transaction, then review patterns periodically. If transport appears again and again, that may be more useful to know than the exact wording of each individual entry.
A fourth insight is to treat the displayed balance as a working signal, not unquestionable truth. It depends on the entries you make. A missing cash sale, a duplicated expense, or a transaction entered under the wrong date can make a precise-looking number misleading. The strongest workflow pairs the app with occasional physical checks, receipts, or payment records. Digital convenience should shorten verification, not eliminate it.
Finally, decide who is responsible for entering transactions. In a small team, a shared cash process can fail if everyone assumes someone else recorded the purchase. Even if only one person maintains the book, the rule should be clear: transactions are entered immediately or handed over with enough detail to avoid guesswork. This is a management habit around the app, but it determines whether the app remains accurate.
What may feel limiting in real use
The focused design can feel restrictive if you expect a complete financial control center. Users looking for bank connections, automated transaction imports, sophisticated forecasting, or formal accounting reports may find that a cash-entry approach does not go far enough. I would not install it expecting it to replace an accountant or a mature business finance platform.
There is also an unavoidable dependence on discipline. The app cannot make an unrecorded transaction visible. If you regularly postpone entries, the balance will become less trustworthy no matter how convenient the interface is. People who dislike manual tracking altogether may be happier with a service that connects directly to their accounts, provided that service suits their privacy and financial needs.
The rating of 3.8 is another reason to approach it as a practical tool rather than a perfect one. A score like that does not make the app unusable, but it suggests that some users encounter friction. My advice is to test the core routine with real transactions before reorganizing your entire business around it. If entering and reviewing money feels natural after several working days, the app is probably a reasonable fit. If the process already feels unclear, more usage is unlikely to solve the underlying mismatch.
Version 8.7.3 is the current release, and the Android requirement is modest enough for devices running Android 7.0 or newer. That makes it approachable for people who do not have a recent phone. Still, compatibility alone should not decide the purchase or download decision. The real question is whether the app’s manual cash-flow method matches your operation and whether you can maintain the habit without creating a second layer of paperwork.
Privacy and operational caution are sensible with any business-finance app. I would avoid entering information that does not help with the cash record, keep descriptions professional, and make sure the phone itself is protected. I would also retain important receipts and supporting records separately when they matter for taxes, reimbursement, or disputes. A convenient cash book is not automatically a legal archive.
My verdict for different kinds of users
I recommend CashBook to a shop owner, market seller, independent worker, or very small business that needs a fast view of money coming in and going out. It is especially suitable when the main problem is delayed recording rather than complicated accounting. The free entry point makes it easy to try, and the everyone age rating keeps it broadly accessible. If your goal is to finish each day knowing what the cash position should be, this app has a sensible role.
I would suggest skipping it if you need automatic bank feeds, multi-user controls, inventory management, invoicing, payroll, or formal financial statements. In those cases, a spreadsheet may offer more flexibility for a careful operator, while dedicated accounting software will usually be the better long-term choice for a growing business. A simpler tool is not automatically a better tool; it is better only when its limits line up with the job.
For me, the decisive advantage is the reduction of mental bookkeeping. The app turns scattered daily events into a single cash-flow habit, and that can save time precisely because it prevents later reconstruction. Its weakness is the same thing: you must enter the events yourself and interpret the result responsibly.
My final recommendation is to use it as a disciplined daily cash book, not as a promise of complete financial management. Start with a verified opening balance, record income and expenses promptly, label withdrawals clearly, and compare the closing figure with reality. If that workflow solves your recurring problem, CashBook - Balance & Expense is a practical business companion. If your needs have already moved beyond simple cash visibility, choose a more comprehensive system before the limitations become another source of work.
CashBook - Balance & Expense FAQ
What is CashBook - Balance & Expense used for?
CashBook - Balance & Expense is a personal finance app designed to help you record income, expenses, transfers, and account balances in one place. After testing its workflow, I found it most useful for everyday budgeting, cash tracking, and reviewing spending habits. It is aimed at individuals who want a simpler alternative to complex banking or accounting software.
Can I use CashBook - Balance & Expense to manage multiple accounts?
Yes, the app is intended to help users organize money across different accounts, wallets, or cash sources. You can generally separate transactions by account and monitor the balance of each one, which is useful when managing cash, bank funds, savings, or shared household expenses. However, users should check the current app version for exact account limits and supported account-management features.
Does CashBook - Balance & Expense connect directly to my bank account?
CashBook - Balance & Expense primarily works as a manual money-tracking tool rather than a replacement for online banking. You should not assume that it automatically imports transactions from every bank or synchronizes balances in real time. Manual entry gives you more control and can be useful for privacy, but it also means that accurate reports depend on recording purchases and income consistently.
Can I create reports or analyze my spending in CashBook - Balance & Expense?
The app is built around transaction records, categories, balances, and expense monitoring, so it can help you understand where your money is going. Depending on the installed version, available summaries may include category-based views, date filters, balance information, or visual reports. These tools are helpful for spotting recurring spending, although the app should not be treated as professional accounting software.
Is CashBook - Balance & Expense safe for storing financial information?
Before entering sensitive financial details, review the app’s permissions, privacy policy, backup options, and any available security settings. The app may store records locally or through an optional backup system, depending on its configuration and platform. Avoid entering unnecessary banking credentials, keep your device protected with a lock screen, and make regular backups if the app contains important financial history.